Legislation
CCTA's progress report warnings for overseas businesses
Companies House’s Economic Crime and Corporate Transparency Act (ECCTA) progress report reveals impressive gains since last autumn. But with the transitional deadline approaching (the November 2026 due date for presenter measures has been revised to no earlier than November 2027, source gov.uk). Companies House, accountants will play a critical role in helping UK and overseas clients meet new compliance and reporting obligations and avoid falling foul of regulators, writes Meg Ogunsola, global head of entity management at Vistra.
Companies House is no longer simply the UK's company registrar. As the latest ECCTA progress report shows, it is becoming an active regulator of corporate data, with stronger powers to challenge inaccurate filings and greater expectations of the businesses it oversees.
Less than a year ago, research painted a worrying picture of readiness, with many firms still unclear on their obligations and more than half of surveyed directors admitting their organisations were not yet compliant with the incoming identity verification rules.
Meg Ogunsola, global head of entity management at Vistra
Since then, millions of individuals have verified their identities and linked their appointments, while thousands of inaccurate or suspicious records have been challenged or removed.
This progress is welcome, but it’s no reason for complacency. With the deadline now only months away, the gap between regulatory momentum and corporate preparedness remains a serious risk.
This risk is amplified for international groups with UK corporate interests. Coordinating governance data, identity verification and statutory filings across multiple jurisdictions introduces layers of complexity that take time to untangle. For accountants advising these clients, the challenges are both regulatory and logistical.
For accountants, identity verification is only one element of a much broader governance challenge. Compliance now requires helping clients maintain accurate governance records, meeting evolving reporting obligations, submitting statutory filings, as well as preparing for identity verification.
The months ahead present an opportunity to help clients address these issues before it’s too late. Those that have not yet acted must do so immediately, not only to avoid fines and filing disruptions, but also to ensure their governance data can withstand a more active, better-resourced, and more assertive Companies House.
Dr Jeremy Osborn, FCMA, CGMA, FCPA (Aust.), Global Head of Sustainability, Chartered Institute of Management Accountants (CIMA)
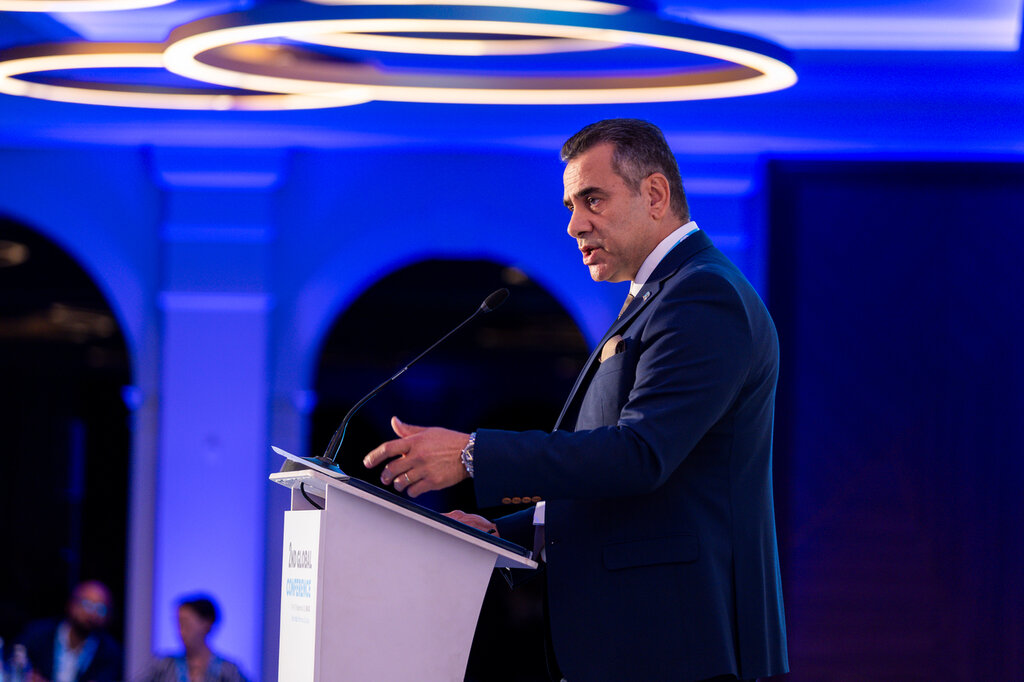
Christos Christodoulou, CEO, Delphi Alliance
"Combined global turnover is not the metric by which we measure success," states Christos Christodoulou, founder and CEO. "What matters is how effectively we collaborate to support our clients - and our growing presence on the geopolitical stage. Reaching IAB Top 20 in four years was a fantastic recognition, but even more importantly, it signals that the industry is beginning to acknowledge that the future of professional services isn't about size alone. It's about the depth and breadth of what you can deliver."
ECCTA’s impact
When ECCTA was introduced in October 2023, it was widely regarded as the most significant reform of Companies House in its 182-year history. Its ambition was to improve the reliability of the UK company register, making it harder to abuse corporate structures and giving Companies House the powers needed to challenge suspicious or inaccurate information.
The latest progress report shows those powers are having a tangible effect. Since mandatory identity verification began in November 2025, nearly four million individuals have verified their identities and linked their appointments. This is a major jump from last autumn, when many businesses were still treating the requirements as a future concern.
Companies House has also made visible progress in cleaning up the register itself. Since March 2024, 151,000 company addresses have been removed, helping to protect individuals and businesses from identity hijacking and misuse. Its deeper collaboration with law enforcement partners has contributed to millions in suspected criminal proceeds being seized.
For accountants, the scale of these developments reinforces the importance of ensuring client records are accurate before statutory filings are made. As Companies House expands its oversight, advisors will need to actively help clients identify and resolve inconsistencies rather than assuming filings will be accepted at face value.
This is particularly important for multinational groups. The complexity of coordinating and maintaining accurate details and filings that reflect wider group structures is additionally challenging. Early preparation is crucial to avoid increased regulatory scrutiny and subsequent disruption.
A more active Companies House
The Act has significantly expanded the powers available to Companies House, giving it a more active role in supervising companies, improving the accuracy of the register and tackling misuse of UK corporate structures. The regulator now has more tools to question information, remove inaccurate details and work with other agencies where suspicious activity is identified.
This comes at the same time as broader corporate accountability is tightening. The failure to prevent fraud offence, which came into force in September 2025, has raised expectations on large organisations to show that they have reasonable procedures in place to prevent fraud.
Identity verification became mandatory for new directors and PSCs in November 2025 under the phased implementation programme. It's central to preventing individuals from hiding behind false identities, nominee arrangements or opaque corporate structures.
Specifically, this means ensuring clients understand who must verify their identity, when verification needs to be completed and how it exists alongside ongoing filing responsibilities. Businesses with overseas directors or PSCs will face additional logistical challenges in coordinating verification, making early action crucial.
These reforms require companies to know who controls them, understand the integrity of their data, and maintain records that are accurate and capable of withstanding external scrutiny. Reviewing PSC information, registered office details, statutory registers and internal reporting processes are all necessary to remain consistent with Companies House records.
But while legislation is one part of the picture, implementation is the other. Millions of individuals still need to verify before the transition period ends. For firms that have delayed, the window to act is narrowing quickly.
The greater risk is that organisations discover too late that records are incomplete, outdated or inconsistent. For international groups, aligning this information across jurisdictions can take considerable time. In these circumstances, identity verification can have a broader impact on statutory filings, corporate transactions and wider compliance obligations.
What firms and accountants must do next
Firms must prioritise identity verification immediately. Accountants must prioritise identifying clients who are yet to complete verification, correcting inconsistencies in governance records, and helping businesses prepare well in advance of filing deadlines.
Verification should prompt a wider review of corporate governance data, including directors, PSCs, registered office addresses, filing responsibilities, and internal records of ownership and control, rather than being viewed as a tick-box exercise. Ongoing governance reviews should be treated as just as important as identity verification itself.
But for organisations with complex structures, multiple entities, international directors or large numbers of PSCs, early preparation is even more critical. Governance information and reporting requirements need to align both locally and across the wider group structure. For international groups managing entities across multiple jurisdictions, specialist entity management support can make the difference between reactive firefighting and proactive compliance.
The era of treating Companies House compliance as low-risk admin is over. Maintaining accurate records year-round is not optional, with only those who act now able to reduce the risk of penalties, filing disruptions, regulatory scrutiny and reputational damage. Those who delay acting may find that ECCTA becomes a costly reminder of the importance of corporate transparency.
For many organisations, ECCTA will be remembered not for introducing identity verification, but for exposing weaknesses in corporate governance data that had accumulated over years. Those who address these weaknesses now will be far better placed as Companies House continues its shift from registrar to regulator.
Main video credit: danger360/Shutterstock.com