Rankings report: Uruguay
Uruguay’s reforms to benefit whales and minnows
Uruguay’s reforms are targeted at attracting large scale investors while turbo boosting its own SME community. Che Golden reports.
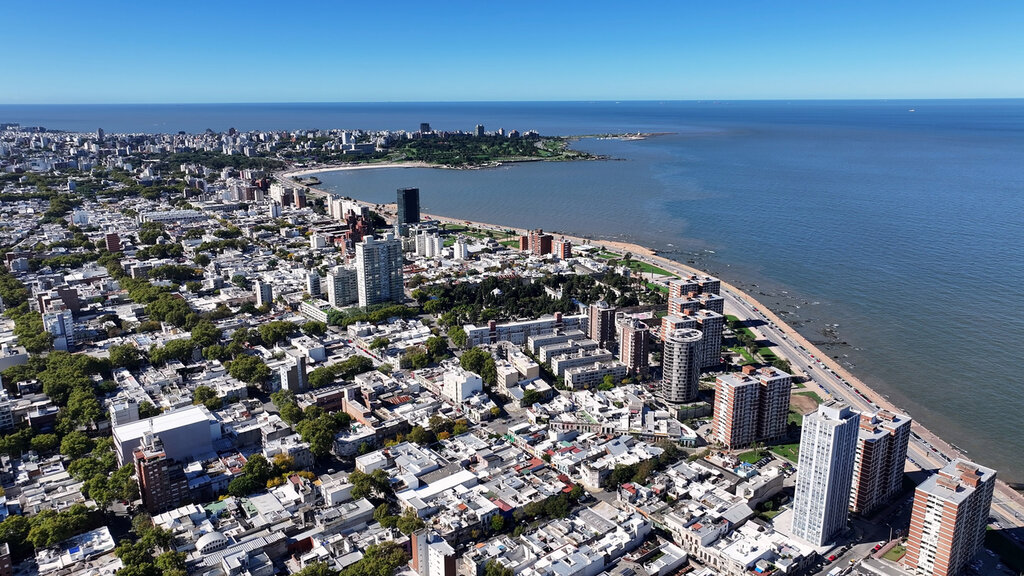
Uruguay is a country that has proved to be remarkably resilient in the face of the increasing political polarisation sweeping the globe. A country free from boom and bust, but with a small local market, local accountancy firms need to generate growth not only by adding value for local clients, but also by attracting international firms with their specialist needs as they settle into the country.
Recent tax reforms have sent a signal to the foreign investment community that not only is Uruguay offering stability, but it is now offering it to a certain type of investor, by raising the cost of entry.
“The most relevant tax amendments in Uruguay between September 2025 and September 2026 fall under the 2025-2029 National Budget Law” said Bruno Foggiato, founding partner at Russell Bedford Uruguay. “The taxable base on Personal Income Tax (IRPF) on foreign-source income has been broadened to include foreign-source movable and real estate capital returns, as well as capital gains, and now incorporates a controlled foreign company (CFC)-style transparency regime that attributes such income directly to the ultimate beneficial owner.
Bruno Foggiato, founding partner, Russell Bedford Uruguay
“The real estate investment threshold has been raised to approximately USD 2,000,000,” he continued. “Existing beneficiaries retain their current benefit, while new residents may elect, on a one-time basis, between the Tax Holiday exemption or a fixed annual IRPF rate for 20 years. The BONT (low- or no-tax jurisdiction) requirement has been eliminated. Any sale of a non-resident entity with a "significant connection" to Uruguay (more than 50% of its underlying assets located locally) is now subject to Corporate Income Tax (IRAE) or Non-Resident Income Tax (IRNR).”
Dividends paid to non-residents have a new IRNR taxable event introduced for cases where the beneficiary's home jurisdiction taxes those dividends and grants a foreign tax credit for Uruguayan withholding, while a new levy targeting multinational groups with consolidated revenues exceeding USD 750 million, is applicable where the local effective tax rate falls below 15%, as regulated under Decree 325/025.
What is so significant about the recent reform is that for almost a decade, Uruguay’s pitch to international wealth was relatively low: roughly USD 590,000 in real estate plus about sixty days of presence unlocked an eleven-year tax holiday on foreign income. Yes, Uruguay is still offering stability but now it is targeting high net worth capital that brings stable funds, rather than the mid-range investor.
The impact that US policy has had on its normally stable economy proves the need for Uruguay to jump start large scale investment into the country. In January, the Uruguayan peso strengthened more than comparable currencies and moved to the top of global foreign exchange performance. As a result, the dollar fell 3.1% in the local market, a deeper decline than those recorded in Brazil, Chile or Colombia.
The weakness of the US currency was closely linked to economic policies promoted during the first year of the Trump administration, especially on trade. The problem is that Uruguay's economy was already expensive in terms of the dollar before this episode. That combination hits exporters hardest because they are paid in dollars while many of their costs are in pesos. When the exchange rate falls, the margin between income and expenses shrinks. Uruguay exports 70 per cent of what it produces, making it very dependent on foreign currencies.
In order to protect itself from currency shocks, amongst other things, Uruguay's Senate unanimously approved the government's Competitiveness Law in August, in a bid to dramatically improve the business environment. The 240 articles cut red tape, ease imports, strengthens competition and open crowdfunding to large companies. It is not yet law and details are going to be subject to later regulation. The bill now passes to the Chamber of Representatives for a second vote before it becomes law.
The key point for businesses is the Uruguay Competitiveness Law opens collective financing platforms (crowdfunding) to large companies. Uruguay legalised crowdfunding in 2019, and the central bank regulated it in 2021. Its rules capped issuing companies at roughly USD 11 million of annual sales, which kept big firms out.
The central bank keeps its licensing role over the platforms themselves. Investor protections built into the 2021 rules, including segregated accounts, remain in place. The bill also creates an open finance regime for banks and fintech firms. Customers will be able to share their financial data between providers. These changes will make it easier for companies to set up in Uruguay and promote new sectors such as Fintech.
Raul Diaz, secretary of the College of Accountants, has welcomed the law, pointing out that regulatory uncertainty has an economic cost on investment decisions that is rarely quantified.
Diaz was part of a committee that worked with the government to outline the new law. From the accountancy perspective, there are three central aspects. The first is the quality of public information systems: reliable, accessible, and internationally comparable data reduces uncertainty and the cost of operating in the country. The second is the coherence and stability of the regulatory framework, since normative uncertainty has a direct economic cost on investment decisions that professionals see reflected daily in company behaviour. The third is the rationalisation of costs imposed by the public administration itself, that is, every unnecessary procedure, every duplication of information, every non-digitized process, is a cost that mainly falls on productive units of smaller scale. Uruguay has conditions to stand out regionally in these aspects, and this law could be a step in that direction.
SMEs are the main recipients of this reform, according to Diaz. They are the ones that proportionally allocate more resources to compliance with formal obligations, those with less capacity to absorb regulatory costs, and those most affected by regulatory uncertainty when planning. They are also make up the bulk of the clientele for local accounting firms. If the law reduces permitting times, eliminates duplications of information and improves interoperability between agencies, the impact on SME competitiveness can be significant, both in their operating costs and in their capacity to project themselves and integrate into value chains of greater complexity.
However, while all this sounds very positive, auditing in the country has taken a step backward by becoming more onerous for clients.
In October, the Association of Accountants, Economists and Administrators of Uruguay presented before the Finance Committee of the Parliament, its opposition to the inclusion of the audit of financial statements and, especially, of the Limited Review as activities obliged to report suspicious transactions (STR).
The president of the CCEAU, Cristina Freire said that these reports "do not allow detecting money laundering operations, because they are ex post analyses." He added that, in the case of the Limited Review, the requirement will generate negative effects on the costs of small and medium-sized enterprises, which are the ones that drive the country's economy, without providing real benefits to the money laundering prevention system.
The College stated that the Limited Review should be eliminated from the law for technical and practical reasons: its scope is limited, the degree of certainty is lower than that of a complete audit and it is not effective in detecting suspicious transactions. In addition, it imposes a disproportionate responsibility on the professional.
In relation to other aspects of the bill, Freire warned, for example, that the threshold set for criminal activities preceding tax fraud, as well as the scope of other crimes, dropped drastically to USD 16,000 (100,000 UUI). "It is such a low threshold that even in the audits themselves it can be considered a non-material amount, and that it widely reaches the country's SMEs and burdens the accounting firms themselves with costs that, in many cases, cannot be passed on to their clients," he said.
The president said that the Executive's proposal will also generate unnecessary bureaucracy that ends up affecting the normal functioning of the economic system. "There are already impressive databases in organisations such as the DGI or the Central Bank; forcing us now to reiterate that search for information only separates us from our profession," he said.
The CCEAU concludes that the reform of the Money Laundering Law requires substantial corrections. First, it proposes the elimination of the Limited Review from the list of obligatory activities, due to its technical inefficiency and its negative impact on the costs of SMEs. Secondly, it calls for the revision of the thresholds established for previous crimes, considering them disproportionately low and generating ineffective reports.
Agustín Rachetti Perez, partner at MGI Worldwide member firm Bado, Kuster, Zerbino & Rachetti (BKZR)
Agustín Rachetti Perez, partner at MGI Worldwide member firm Bado, Kuster, Zerbino & Rachetti (BKZR), acknowledges the local firms are living in a period of uncertainty. As well as the sweeping changes mentioned previously, AI is bringing its own pressures to bear in terms of skills and resources that firms now have to find, to take advantage of the technology and to meet the demands of clients. “Despite all this, demand has increased, and we continue to see growth,” said Perez. “Fee pressure is very tough, but this is nothing new, it has been like this for ever. Competitors are very aggressive with the fees, and clients often do not value our services.
“Recruitment and retention are the most challenging issues in our industry, we are very concerned about how AI is going to affect our industry, and how new generations will adapt to the new circumstances,” he continued.
Foggiato agreed. “The accounting industry, like many others, is being challenged by the rise of artificial intelligence, which is reshaping both the services offered and the way local and international professional firms deliver them. Locally, we're seeing significant downward pressure on fees, coupled with a relatively tight talent pool,” he said.
In the short term, AI is going to cause the most pain to local firms. Foggiato feels the coming months will be defined by the evolution and internal adoption of artificial intelligence across organisations. “The focus will need to remain on human interaction and on delivering close, personalised advisory to each client,” he said.
Hopefully, simplifying the business environment and attracting large scale investors will give local firms more opportunity for growth in a rather claustrophobic market.
Main image: Montevideo Skyline At Montevideo In Maldonado Uruguay. Credit: ByDroneVideos/Shutterstock.com